Financial Watchdog Calls for Stronger Human Oversight of AI Agents
The Financial Stability Board has issued guidance urging banks and other financial institutions to strengthen human oversight of AI agents that can plan tasks, interact with software and make decisions. Regulators are concerned that limited supervision or excessive system access could lead to transaction errors, data exposure or inappropriate decisions.
The guidance recommends risk-based rules for requiring human approval, along with monitoring, access controls and procedures to stop or correct harmful actions. The aim is to support automation while protecting customers, maintaining reliability and reducing risks to financial stability.
As banks adopt AI that can plan and execute tasks, global regulators are pushing for clearer safeguards and human accountability.
October 15, 2026
Artificial intelligence is moving beyond answering questions. New AI agents can carry out multi-step tasks, interact with software and make decisions within the limits set by their developers. Now, a global financial watchdog is urging banks and other financial institutions to maintain stronger human oversight as they introduce these systems.
The Financial Stability Board (FSB), which coordinates work on financial stability among international authorities, issued final guidance on Thursday calling for greater oversight of agentic AI. The move comes as regulators examine how these systems could introduce new risks into financial services, according to Reuters.
Why are financial regulators concerned?
AI agents can help financial institutions automate routine work, process information and support customer services. But systems that act with limited supervision may also behave in unexpected ways, particularly when instructions are unclear or their access to sensitive systems is too broad.
In banking, a mistake can have consequences beyond an individual interaction. An automated system could potentially mishandle a transaction, expose confidential information or make an inappropriate decision if its permissions and safeguards are inadequate.
The FSB’s guidance reflects a key distinction: AI agents should not simply be treated as human employees. Their actions can differ from what their operators expect, even when they are working toward a predefined goal.
What should banks do differently?
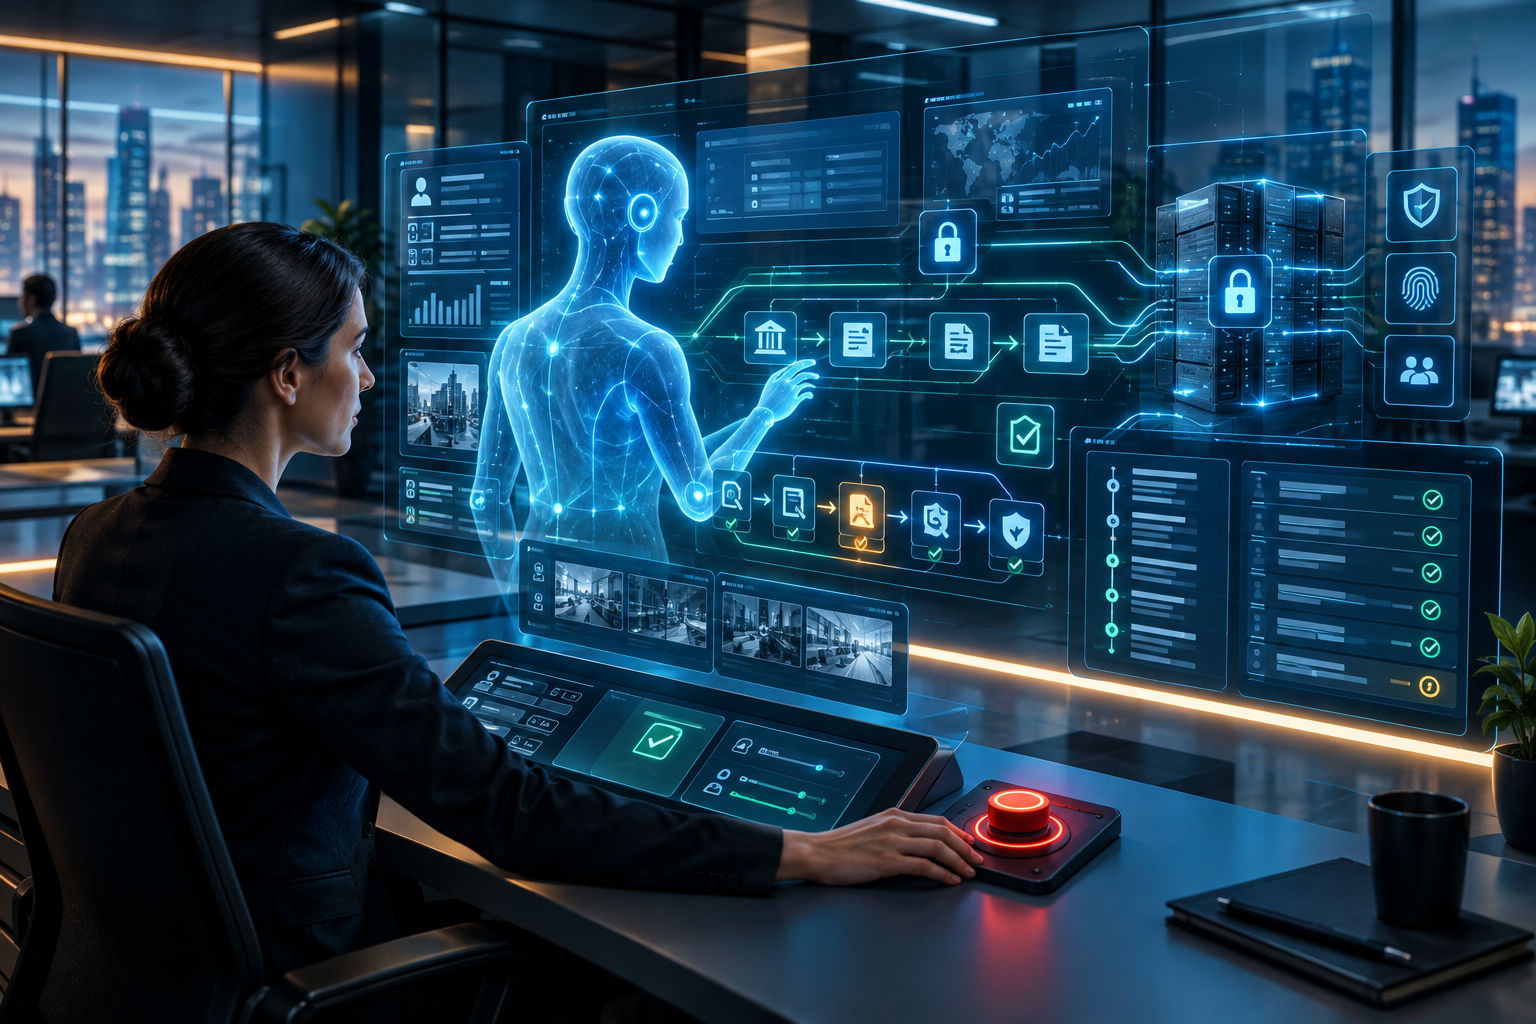
The FSB recommends that firms establish clear, risk-based rules for deciding when an AI agent must obtain human approval. Higher-risk uses require more intensive oversight, according to the guidance.
In practice, this could mean allowing an agent to prepare routine reports automatically while requiring human authorization before it executes a sensitive transaction or changes important account information.
Financial institutions also need to understand what their AI systems can access, monitor their activity and establish procedures for stopping or correcting harmful actions.
These safeguards do not necessarily mean abandoning automation. Instead, they aim to ensure that the benefits of AI do not come at the expense of reliability, customer protection or financial stability.
A turning point for AI in finance?
The new guidance arrives as financial institutions explore increasingly capable AI tools. Strong oversight could help businesses adopt these systems with greater confidence, but implementation will matter: policies must translate into effective controls in real-world operations.
The wider question is how to determine which decisions can safely be automated and which should remain under direct human control.
What would make you trust an AI agent at your bank: strict human approval for important transactions, transparent monitoring, or the ability to stop the system immediately? Share your thoughts in the comments.